Who This Guide Is For
This guide is for real estate investors who are from America, expats, or foreign nationals. It gives detailed information about DSCR financing. This handbook is beneficial to investors whether it is their first time investing in a rental property or whether they already have reached their twentieth investment. It also helps investors whose income or residence may not suit traditional underwriting standards.
The purpose of this guide is to provide an overview of DSCR financing. This will include eligible properties, pricing, and mistakes made by investors. These case studies are fictional examples used to illustrate the learning process and not descriptions of any clients. All figures and programs listed are industry standard estimates.
Contents
- What Is a DSCR Loan, and Why It Changed Investment Financing
- The DSCR Formula, Explained
- Three Qualification Tiers
- No Personal Income, No DTI, No Employment Verification
- LTV, Loan Amounts, and Rates: What to Expect
- Short-Term Rentals and DSCR
- Buying Through an LLC With DSCR
- Portfolio and Blanket DSCR Loans
- Scaling a Portfolio Without a Property Limit
- Common DSCR Mistakes First-Time Investors Make
- DSCR for Foreign Nationals and U.S. Expats
- Frequently Asked Questions
- About This Guide
1. What Is a DSCR Loan, and Why It Changed Investment Financing
A DSCR mortgage is an investment property mortgage. The main qualification of the property is made based on the rental income generated by it. It does not depend much on the personal income and employment of the applicant. The underwriting considers if the rental income will cover the debt service of the property.
This is a very big change in investment finance within the last ten years. It involves avoiding many of the paperwork requirements that pertain to personal income. It can help independent investors, foreigners, and expatriates with income from abroad. It can even assist retirees with no need for salary but with assets. There are investors who just want more privacy in buying rental property.
2. The DSCR Formula, Explained
DSCR = Monthly Gross Rental Income ÷ Monthly Debt Service (principal, interest, taxes, insurance, and HOA dues where applicable)
When the DSCR is 1.00, the rental income just equals the cost of servicing the debt. If the ratio is above 1.00, there is money for a payment buffer. If the ratio is less than 1.00, this shows that the rental income is not sufficient to service the debt on paper.
3. Three Qualification Tiers
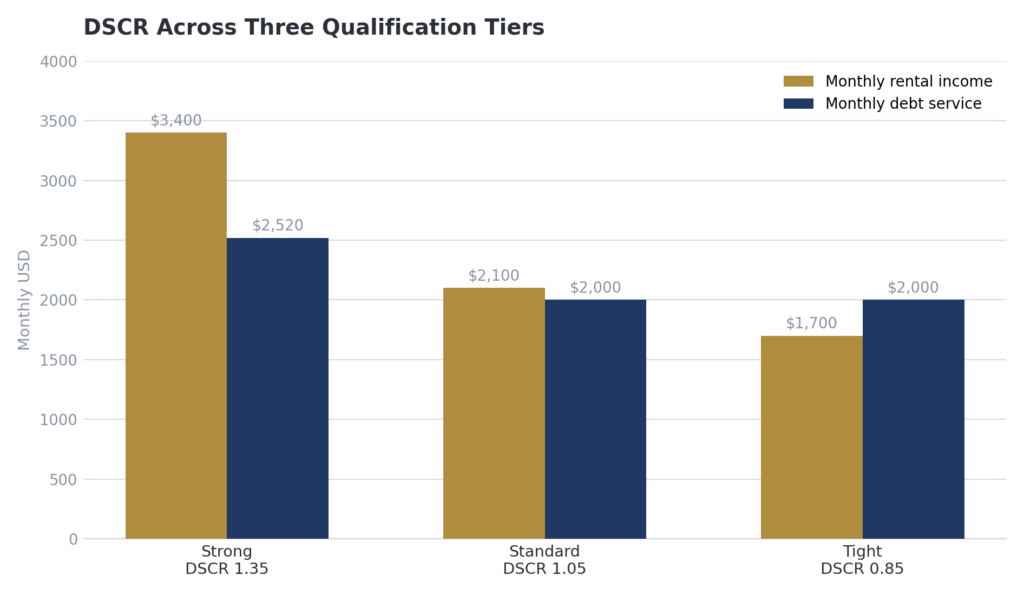
Illustrative examples across three common DSCR tiers. Actual thresholds and pricing vary by lender and program.
Strong: 1.20–1.25 and above
This type of property usually qualifies for the best possible price and leverage. The difference between $3,400 rent and $2,520 cash flow ($780 excess) is well within the lender’s preferred DSCR.
Standard: roughly 1.00–1.20
This range is usual in simple rentals. The rent is sufficient to cover the cost with some extra. The pricing is usually normal with no premiums or discounts.
Tight: below 1.00
Other lending programs might also fund projects with a DSCR ratio that is lower. Rates, reserves, and leverage can all be modified to compensate for the lower income. A DSCR ratio of 0.85 does not mean automatic disapproval. The loan will have different pricing and terms.
4. No Personal Income, No DTI, No Employment Verification
DSCR loan programs normally do not consider personal tax returns in the underwriting process. Paychecks, stubs, and proof of employment are generally not required either. Personal debt-to-income ratios are normally not considered either. DSCR is thus perfect for self-employed individuals, foreigners, and expatriates. Income earned overseas need not be accompanied by proof of income earned domestically.
What DSCR does still require:
A down payment (typically 20–25% or more), reserves, an appraisal supporting the property’s market rent, a credit evaluation (domestic or international), and a clean title. DSCR removes personal income from the equation — it doesn’t remove underwriting altogether.
5. LTV, Loan Amounts, and Rates: What to Expect
A DSCR purchase and a cash-out refinance have the ability to go up to about 80% LTV. The terms for strong borrowers and assets might be extended even further. Terms may be different depending on the borrower or property risks. The minimum loan size varies from lender to lender. There may be some that start at $75,000-$100,000 or there may be those that focus on larger loan amounts. Programs based on DSCR typically do not have a cap on the number of loans.
The DSCR loans tend to have high interest rates compared to those of traditional mortgages. The reason for this is the inherent risk in the investment property. The lower level of income information can be another factor that affects pricing.
6. Short-Term Rentals and DSCR
Income from short-term rentals through Airbnb, VRBO, and other similar websites may be eligible for DSCR loans in many cases. However, different lenders have different requirements in this regard. While some may ask for income projection on the basis of market data, others may demand that the short-term rental schedule be prepared by an appraiser. Sometimes, actual rental income may be asked for from the particular property.
ILLUSTRATIVE EXAMPLE
Marcus Fielding — remote investor, Airbnb portfolio
Marcus wanted to finance a beach-market condo based on its strong Airbnb income potential, well above long-term rental comparables. His first lender would only credit standard long-term rent, producing a DSCR under 1.00 and weaker pricing.A program built around short-term rental underwriting used a market-based short-term rental schedule instead, pushing the qualifying DSCR to 1.30 and materially improving his leverage and rate on the same property.
7. Buying Through an LLC With DSCR
It is common practice to close DSCR loans in the name of an LLC rather than in one’s personal name. Some DSCR programs accommodate such a loan setup. There are liability protection benefits from utilizing an LLC for the investment property. Both U.S.-based and foreign-based LLCs could qualify under some programs depending on the requirements set by the lenders.
8. Portfolio and Blanket DSCR Loans
For investors who own multiple properties, a portfolio loan or blanket DSCR loan is worth considering. It allows multiple properties to be financed with one single loan. It may be more cost-effective than having to finance each property individually. Such types of loans are more favorable for large portfolios. If there is just one or two properties, individual loans are more convenient.
9. Scaling a Portfolio Without a Property Limit
Traditional agency lending normally restricts financing to 10 financed one-to-four family units. The DSCR loan evaluates each individual unit’s financial standing. It does not normally restrict its financing according to the number of financed units. For this reason, the DSCR loan is preferred by many investors who intend to make large investments.
ILLUSTRATIVE EXAMPLE
Isabelle Laurent — Paris, France
Isabelle began with a single DSCR-financed Georgia rental five years ago. Using the equity-recycling approach — refinancing each seasoned property to fund the next purchase — she now holds seven financed properties, a scale that would have run into conventional agency limits well before this point.
10. Common DSCR Mistakes First-Time Investors Make
- Assuming that any rental estimate would be acceptable: Lenders usually need an appraiser’s rental estimate for the market.
- Underestimating reserve funds needed: Most programs will need some months of additional payments beyond the down payment.
- Not accounting for short-term rental income: It’s important to know how lenders view short-term rental income before using it.
- Failing to take into account carrying charges: Be sure to include any HOA fees, flood insurance, and other costs in your DSCR calculation.
- Failing to compare lenders: DSCR requirements and cost can vary greatly among lenders.
11. DSCR for Foreign Nationals and U.S. Expats
DSCR is a quick route to getting money for investments in properties in America. It is possible for foreign individuals and expatriates from America to use this type of loan. The loan emphasizes property income rather than personal income. As a result, there are fewer documentation problems that arise when using this type of loan compared to traditional loans. Foreign pay slips might not require translation. FEIE tax returns will not need to be analyzed in detail. Most programs also do not require a U.S. credit score.
12. Frequently Asked Questions
Q1: What is a DSCR loan?
The DSCR mortgage loan considers an investment property according to the amount of money earned from rent and debt servicing. The consideration of personal income is minimized.
Q2: What DSCR ratio do I need to qualify?
A lot of the programs are looking for a ratio of 1.00 or above, with the best pricing generally available over 1.20-1.25. There are programs that will still evaluate properties with ratios under 1.00, even as low as 0.75.
Q3: Do I need a job or W-2 income to get a DSCR loan?
No, the majority of DSCR programs do not need employment verification, W-2 forms, or even tax statements. All that matters is the income from the property itself.
Q4: Can foreign nationals get DSCR loans?
Yes, DSCR is an easy source of finance for foreign national investors. In many cases, a credit score in the United States is not necessary. Income documentation in the U.S. may also be avoided.
Q5: Is there a limit on how many DSCR loans I can have?
Generally no. Traditional agency financing programs allow no more than 10 financed properties for any borrower. DSCR financing programs tend to assess each individual property on its own merits.
Q6: Can I use Airbnb income to qualify for a DSCR loan?
Often, yes. However, different programs have different approaches to short-term rental income. While some will base the income on estimates from the market, others might ask for proven short-term rental income from the specific property.
Q7: Can I close a DSCR loan in an LLC?
Yes, this is typical. Many DSCR programs are designed for LLC owners. Some even permit LLCs owned by foreigners.
Q8: How much down payment do I need for a DSCR loan?
Typical down payments will be anywhere between 20% to 25%, and possibly even higher. The maximum LTV can go up to around 80% for good credits. Properties with a good DSCR may also be eligible for high LTV.
13. About This Guide
The guide is a completely independent educational guide for real estate investors. It includes both domestic, expatriate and foreign nationals borrowing. The guide is based on the knowledge from America Mortgages. America Mortgages is the U.S. mortgage arm of Global Mortgage Group.
All calculations and descriptions follow the usual industry standards at time of publication. These have been included solely for educational purposes. The following is not intended as legal, tax, investment, or financial advice. It is not an offer to lend. Availability, terms, rates, and underwriting requirements may be different based on specific product, property type, borrower type, and state.
Share this article
Ready to get started?
Speak with our U.S. mortgage specialists today and discover your options.
Schedule a call